
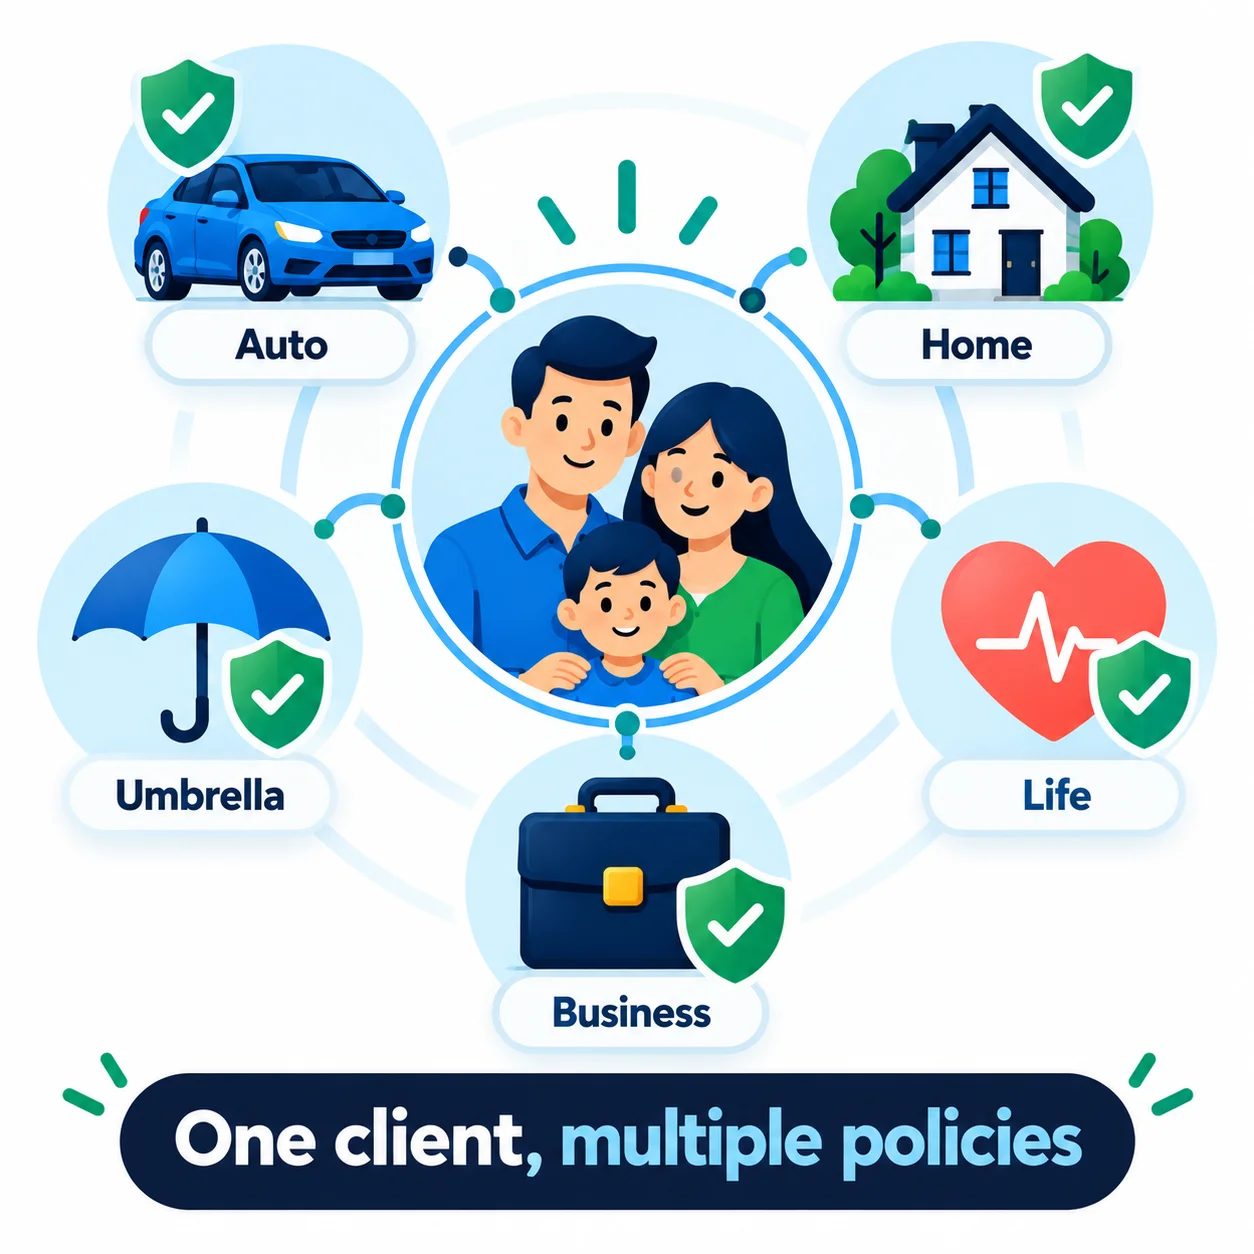
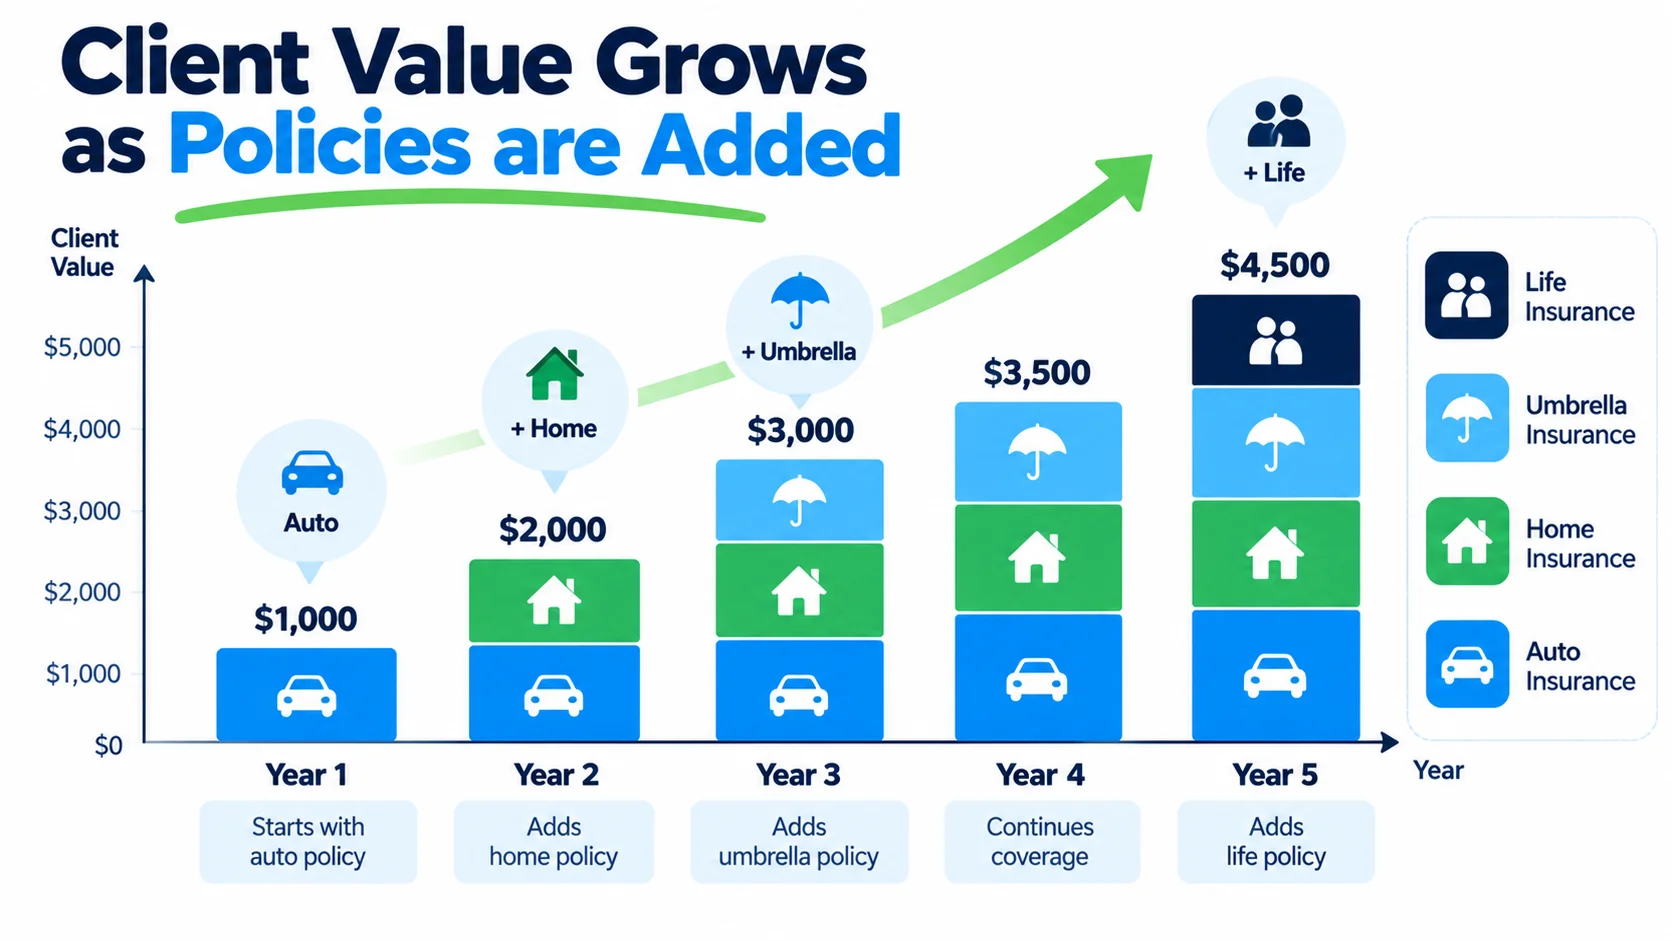
For insurance agencies, the first policy is just the beginning. A client who starts with auto insurance might later add home, umbrella, life or business coverage, and stay for years.
Agencies that scale focus on the whole relationship, not just the first quote.
1. Know Your Client Lifetime Value
Estimate how much commission a typical client brings over several years, including renewals and additional policies. This tells you how much you can afford to spend to win a new client. Our digital marketing ROI guide shows how to work this out.
2. Cross-Sell Thoughtfully
- Auto clients → home or renters insurance
- Homeowners → umbrella policies
- Families → life insurance
- Business owners → commercial coverage
Annual policy reviews are a natural, helpful time to discuss these.
3. Protect Retention
- Proactive renewal check-ins before rate changes
- Quick, helpful claims support
- Birthday and holiday touchpoints
Keeping a client is almost always cheaper than winning a new one.
4. Ask for Referrals and Reviews
Happy clients refer friends and family. A simple referral program and consistent Google review requests add steady growth.
5. Scale Ads Based on Lifetime Value
- Track which campaigns bring clients with multiple policies
- Invest more in high-value lines (for example niche commercial)
- Use Meta retargeting to share cross-sell offers with existing website visitors, following platform rules
The Bottom Line
Insurance agencies scale by thinking in lifetime value: cross-sell thoughtfully, protect retention, earn referrals and invest ad spend where it brings the best long-term clients.
Read Google and Meta Ads for insurance agencies for the basics. See our insurance marketing services.
Related Reading
- Insurance Agency Advertising Budget: Best Platforms and a 3-Month Plan
- Insurance Agency Automation
- CRM for Small Business: How to Choose One and Connect It to Your Ads
👉 Get a free growth audit for your insurance agency.